What counts as a named storm
South Carolina Regulation 69-56 defines a named storm deductible as one triggered by a weather event named, designated or identified by the U.S. National Weather Service or the National Hurricane Center, and only a hurricane, tropical storm or tropical depression. A storm named by anyone else, including a winter storm named by the news media, cannot trigger it.
Disclosure on every policy
An insurer may not issue or renew a policy with a separate hurricane, named storm or wind/hail deductible unless it includes an example of how the deductible works on a policy valued at $100,000, with a clear explanation of the event that triggers it, and prints a warning on the policy face and declarations page that the deductible may result in high out-of-pocket expenses.
Adding or raising the deductible at renewal
An insurer may not add a hurricane, named storm or wind/hail deductible, or increase one, at renewal unless it provides the $100,000 example and the named insured signs or initials a disclosure acknowledging they have read it. The current version of the regulation took effect June 26, 2020.
What a 2% deductible costs
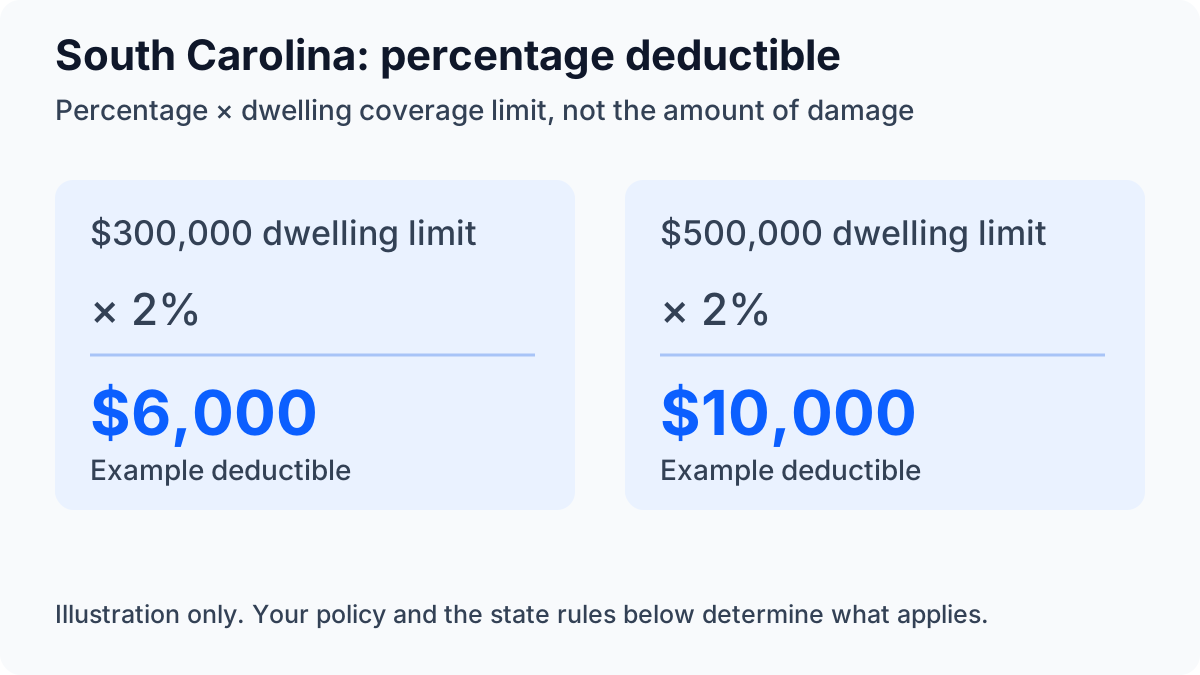
A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.