Landfall in New York is required
The Third Amendment to Insurance Regulation 159 (11 NYCRR 74), effective February 2, 2026, says a hurricane deductible may be triggered only when the National Weather Service determines that the hurricane made landfall in New York. A hurricane is a tropical cyclone with maximum sustained surface winds of 74 mph or higher.
The time window
The deductible applies only to loss from wind damage in the period beginning 12 hours before the hurricane makes landfall in New York and ending 12 hours after the National Weather Service cancels the last hurricane watch or warning it issued for New York for that hurricane.
Where and how it applies
A hurricane deductible may vary by county, by the property's distance from the coastline, or both, and the insurer must show the Department of Financial Services there is enough hurricane exposure to justify one. All covered losses from the hurricane are added together when deciding whether the deductible has been reached.
What the policy must show
The declarations page must show both the percentage and the corresponding dollar amount of the hurricane deductible, and a policyholder notice explaining it must accompany the policy at issuance and renewal.
What a 2% deductible costs
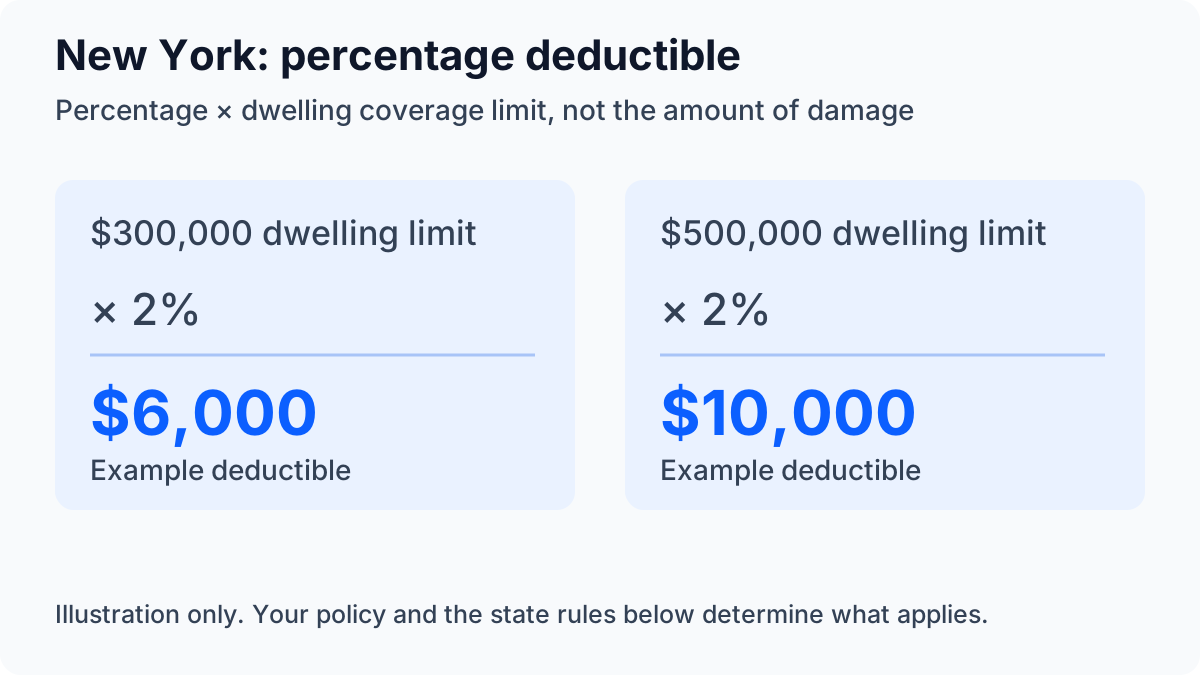
A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.