When the hurricane deductible applies
Under section 627.4025 of the Florida Statutes, the hurricane period begins when the National Hurricane Center issues a hurricane warning for any part of Florida and ends 72 hours after the termination of the last hurricane watch or hurricane warning for any part of Florida. The storm must be one the National Hurricane Center has declared a hurricane.
Deductible choices insurers must offer
Section 627.701(3) requires insurers to offer alternative hurricane deductibles of $500, 2%, 5% and 10% of the policy dwelling limits, with limited exceptions. The written offer must say which hurricane deductible applies if the policyholder does not actively choose one.
Once per calendar year
Section 627.701(5) says the hurricane deductible applies on an annual basis to all covered hurricane losses in a calendar year. For a later hurricane in the same year, the insurer may apply the greater of the remaining hurricane deductible or the deductible for other perils.
What a 2% deductible costs
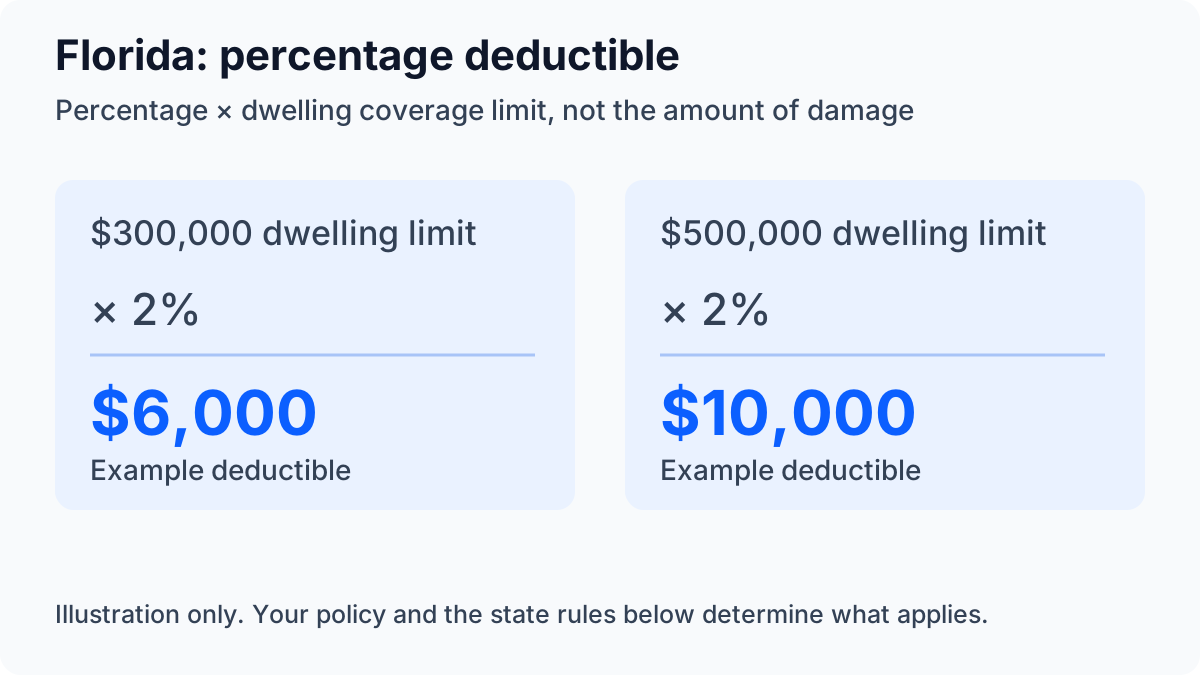
A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.