Louisiana hurricane deductible rules

When the hurricane deductible applies in Louisiana and what it can be, summarised from official state sources.

Louisiana in brief

Louisiana requires a separate named storm or hurricane deductible on owner-occupied one- and two-family homes to apply on an annual basis to all such losses in a calendar year, and requires a separate signed deductible form for new policies effective after January 1, 2023.

Convert your percentage deductible to dollars →

What counts as a named storm or hurricane

Louisiana Revised Statutes 22:1337 define a hurricane as a storm system declared a hurricane by the National Hurricane Center, and a named storm as one declared a named storm by the National Hurricane Center.

Once per calendar year

For homeowners policies and other policies on one- or two-family owner-occupied homes issued or renewed on or after January 1, 2010, a separate named storm or hurricane deductible applies on an annual basis to all such losses in a calendar year. For a later storm in the same year the insurer may apply the greater of the remaining separate deductible or the all-other-perils deductible.

A separate deductible form

The Commissioner prescribes a separate form explaining named storm, hurricane, and wind and hail deductibles. For new policies effective after January 1, 2023 the insurer must provide it and ask the named insured to sign it, and a new form is required when the deductible percentage or dollar amount changes. The form is informational and does not change the policy.

What a 2% deductible costs

A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
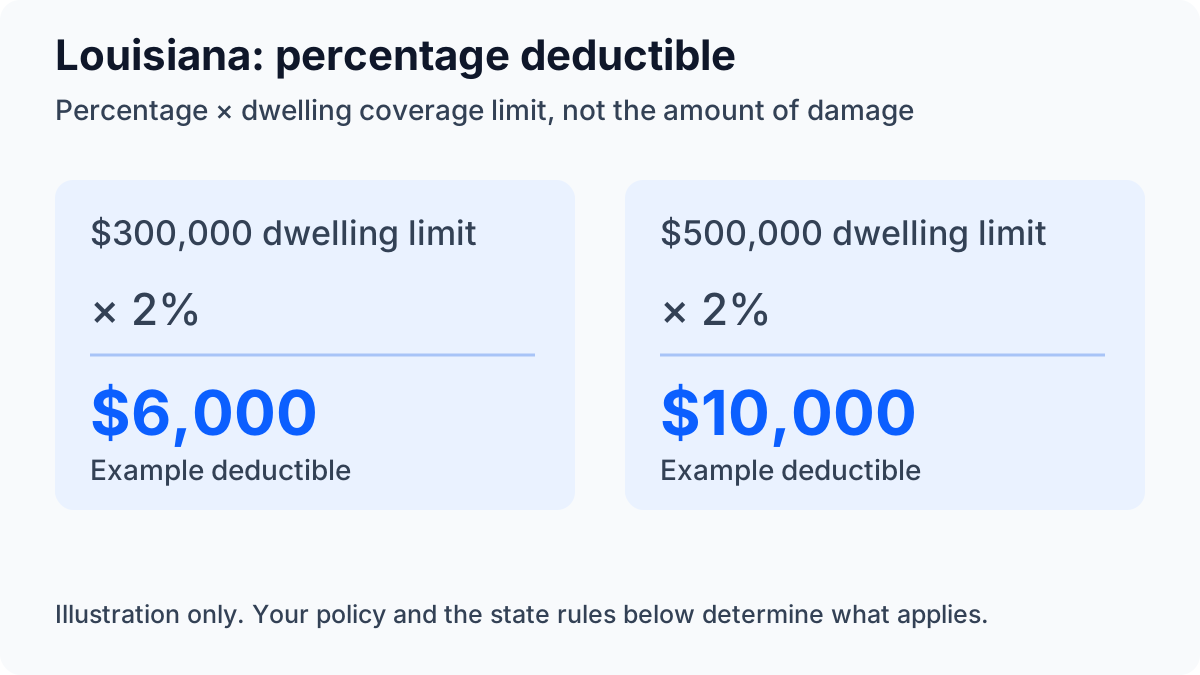
Example 2% deductible: $300,000 of dwelling coverage gives $6,000; $500,000 gives $10,000.
A visual summary of the examples below. The text, applicable periods, sources and limitations on this page govern.

Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.

Frequently asked questions

Is the Louisiana hurricane deductible per storm or per year?

Per calendar year for one- and two-family owner-occupied homes: the separate deductible applies on an annual basis to all named storm or hurricane losses in the year, and a later storm uses the greater of the remaining amount or the all-perils deductible.

What is the Louisiana hurricane deductible form?

A separate form prescribed by the Commissioner that explains named storm, hurricane, and wind and hail deductibles. New policies effective after January 1, 2023 must include it and ask the named insured to sign it.

Hurricane deductible rules in other states

Florida · New York · Mississippi · Rhode Island · Maryland · Connecticut · North Carolina · New Jersey · Texas · South Carolina · Massachusetts

All states · Hurricane deductible calculator

Sources & further reading

Figures read from the official sources below and checked: October 20, 2026. Worked examples are our calculations, not benefit awards.