When the deductible applies
Connecticut General Statutes section 38a-316a allows a hurricane deductible, for policies issued or renewed on or after October 1, 2012, starting no earlier than a National Hurricane Center hurricane warning for any part of the state, if the hurricane results in maximum sustained surface winds of 74 mph or more for any part of Connecticut. It ends at the earlier of 24 hours after the last hurricane warning for the state ends or 24 hours after the storm is downgraded from hurricane status.
Limits by distance from the coast
The Insurance Department's filing review guidelines dated July 25, 2014 allow a hurricane deductible of up to 5% within 2,600 feet of the coast and up to 2% beyond 2,600 feet. For renewals more than 2,600 feet from the coast, the 2% deductible may be applied only if the home does not have storm shutters.
Shown in dollars
The same guidelines require the declarations page to set out the dollar equivalent of every hurricane deductible and to highlight it when the deductible is a percentage of the property's value.
What a 2% deductible costs
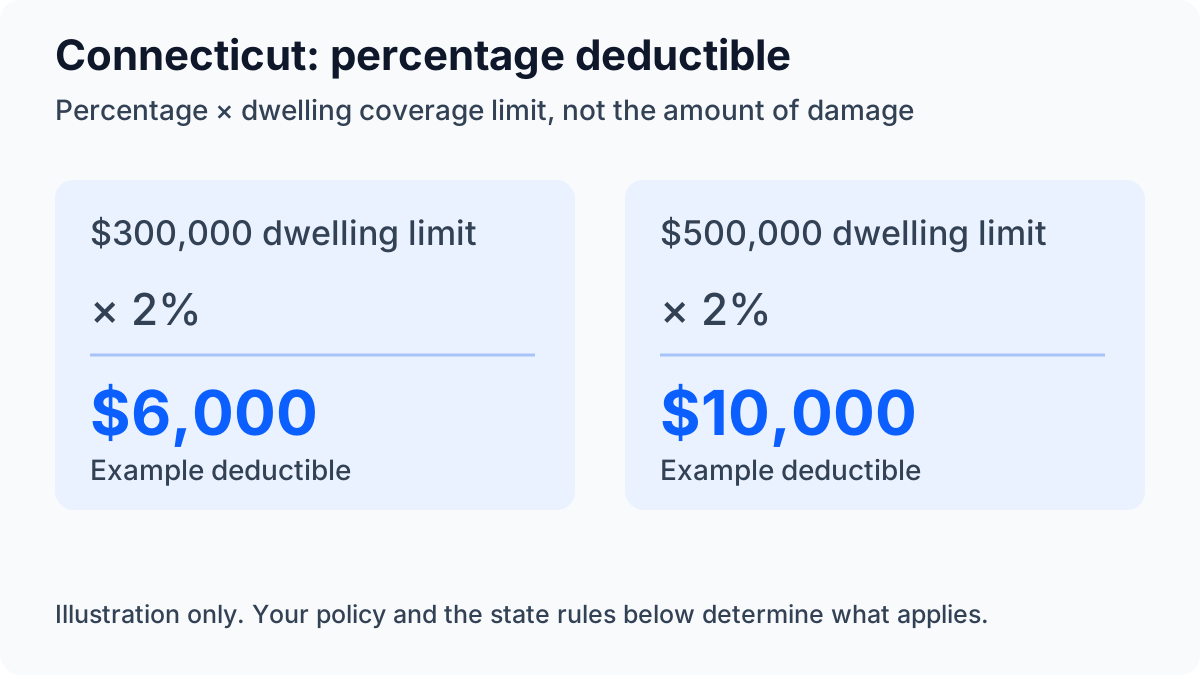
A percentage deductible is applied to the dwelling coverage limit (Coverage A), not to the damage. On $300,000 of dwelling coverage a 2% deductible is $6,000; on $500,000 it is $10,000. Covered storm damage below that amount is paid by the homeowner.
Read your own declarations page and deductible endorsement: the policy wording, together with state law, decides which deductible applies to a loss. This page summarises the official state guidance only.